


Many retirees don’t want to occupy all day every day investing, and have accumulated funds to support their retirement. What are their options?
Perhaps they are happy following the standard advice to hold a 60/40 portfolio using index funds and to do the archetypal 4% withdrawals, escalating with inflation. However, a thoughtful look at the real pricing of the S&P500 might give them pause. Down decades are common and we seem due for one now.
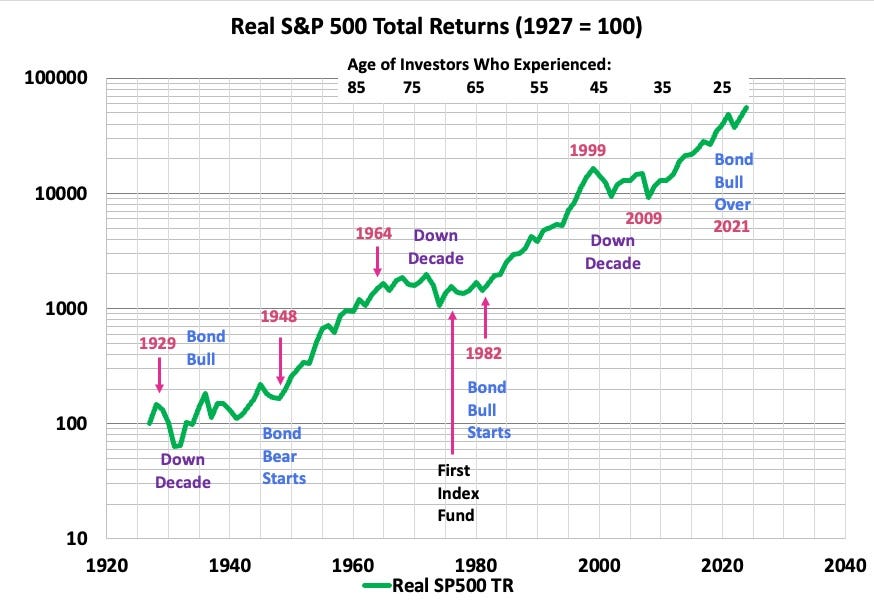
They may realize that real dividends from solid firms suffer much less, and often increase, in those flat decades. They may wonder where to find such dividends, and how large they may be.
Another group that asks this same question is the hands-on real estate investors who hope to give up the required legwork. They often would rather see income from actual earnings and not from the airy-fairy behavior of stock markets.
Questions from that second group is what prompted me to begin this portfolio, two years ago. At the time it was entirely focused on REITs. But with the advent of this Substack, it is time to add energy investments, a big part of my overall portfolio.
Why Earnings from Hard Assets?
The two areas I just mentioned involve companies whose earnings come from the economic use of hard assets. To my mind this is key.
A company offering services can see their products overtaken by the next generation, or just the next fad. Remember MySpace?
Or their management can make a bad decision, burning up shareholder capital. Often this involves debt-driven expansions, as we’ve seen with countless restaurant chains including Boston Chicken. It also can involve really dumb decisions, such as the one by Hertz to go all in on EVs.
A company offering products can easily find their products obsolete. Once mighty Intel (INTC) is struggling to cope with that today.
In contrast, well-managed hard assets are less vulnerable. Real-estate assets retain value so long as they can be rented for more than operating costs.
This is not a sinecure. We have seen some malls and some office buildings become non-economic during the past decade. But more often troubled buildings are carrying too much debt and do have an economically viable future after that debt is quenched by banckruptcy.
Similarly, there is an enduring demand for energy, to power human activities. Energy transport systems (especially pipelines and associated infrastructure) serve that demand, are cheap to maintain, and rarely will become obsolete.
[And if you think renewables are going to displace that then do some research. They will not.]
In those cases, too much debt can again cause trouble. Investors must pay attention to that.
I personally tend to avoid utilities. They do serve enduring demand but are often very impacted by local politics via state-level, public-service commissions.
Looking for Stability
Recall that the point here is to find companies that can be ignored for a year at a time, so that you can spend your time fishing and not investing. There is a great Warren Buffet quote relevant to this:
I try to invest in businesses that are so wonderful that an idiot can run them. Because sooner or later, one will.
Of course you don’t want to invest in one if you know an idiot is running it. But you want to be OK if it turns out, a year later, that one is.
My criteria for finding such companies are these:
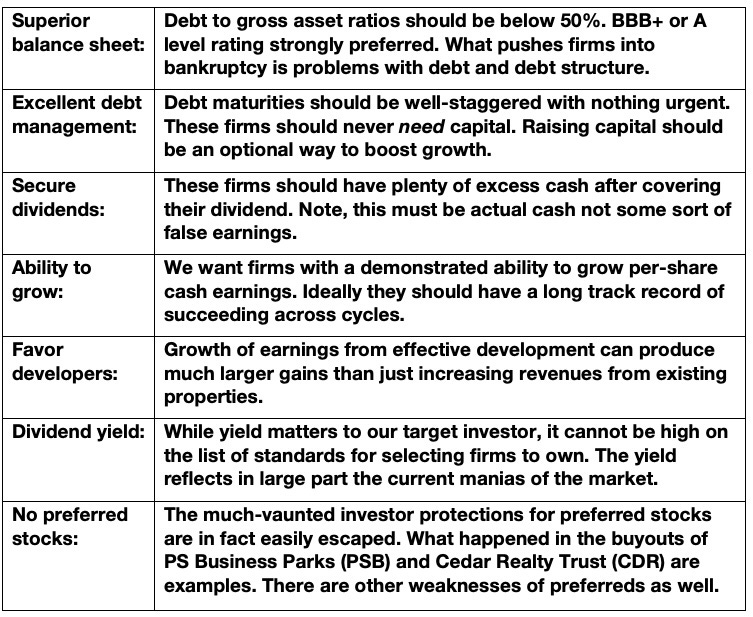
There are two connected kinds of risk for such a portfolio. First, a dividend might be cut, reducing your income.
I recently published an analysis of this aspect using a Monte Carlo evaluation of losses. The bottom line was this: to assure that real income will remain above spending on timescales above 20 years, you need to start with surplus income. A surplus of 10% is sufficient for 21st-century rates of dividend cuts, and you get a lot more cushion going up from there.
Second, you might decide that you need to move on from some company (and its idiots), and be unable to completely replace the income at the same level of risk. This would be a self-imposed income cut.
We’ll flesh this out by discussing the specific case of W.P. Carey (WPC).
W.P. Carey (WPC)
At the time of my 2023 Go-Fishing Portfolio, I included WPC despite the fact that they did not meet all the criteria. My view was that they were past their problems and would be growing their dividend with inflation or more going forward.
Then they turned around, spun off their office properties, lowered their target payout ratio, and cut the dividend by 20%. That demonstrates my misjudgement of where they were six months earlier, but also positions them better to grow the dividend going forward.
By itself that is not a severe blow in the Go-Fishing context. Even holding as few as 10 positions, that cut would reduce income by only 2%. That would likely be overcome by dividend growth, though you would not want that headwind every year.
So I left WPC in the Portfolio for 2024. After that two things happened that shook my confidence.
First a major tenant in Europe faced financial troubles. This led, from that tenant, to some months of lost revenues and a forward rent reduction of 11%. Second, the CEO said some really dumb things on two earnings calls.
Here is where it gets interesting. Had I been a Go-Fishing investor, I would only now know of all this and be faced with deciding whether to sell WPC or not. Aspects to this:
That 6.4% dividend yield is hard to replace at low risk.
The loss of income on those funds, from switching to NNN REIT (NNN), would be an additional 17%, on top of the 20% already.
The WPC dividend is not actively threatened. Most likely it will be sustained and a next cut would likely not exceed 20%.
One could gain income by moving those funds into EPR Properties (EPR) or Armada Hoffler (AHH). But those are not Go-Fishing REITs.
For an existing Go Fishing investor today, I would not object to moving the money into NNN or to holding WPC for another year before considering it again. But the portfolio below, focused on where to put new money in this area, will not include it.
(For my own portfolio, last August I sold WPC and put the money into Camden Property Trust (CPT) for upside and into Sila Realty Trust (SILA) for income. This was not in either case focused on Go-Fishing income, although CPT is such a REIT. )
Performance of the 2024 Portfolio Companies
Here are the relevant outcomes for the 2024 Portfolio. Note that price return is NOT one of them.
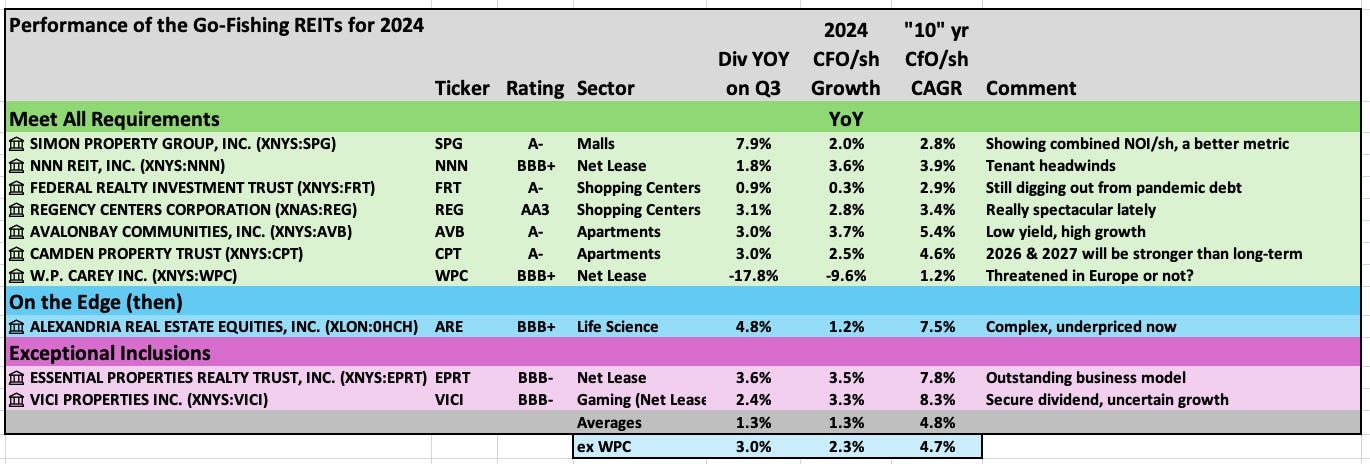
Leaving aside WPC, discussed above, the others averaged a 3% growth rate of the dividend and 2.3% growth of CfO/sh. The WPC cut was in 2023, so this year it did not detract from growth.
Overall, the dividends kept income roughly even with price inflation (ignoring WPC). This perspective is mine, where there are positions that grow, adding income, and other positions that are problems. The intent is to make that second group zero.
The low growth rates by Federal Realty (FRT) are not misleading, as they continued working down their pandemic debt. They are about done with that. For Simon Property Group (SPG), a more complex story, it made more sense to me to replace, in the table, the growth of CfO/sh with that of the combined, beneficial cash NOI/sh.
For the apartment REITs, the growth of CfO/sh in 2024 is well below the 10-year average. It is an open question, going forward, whether continuing interest-rate headwinds will have a bigger impact than improvements in apartment supply dynamics and other positives.
One can also look at the combined gains in the first two years of the portfolio (2023 & 2024). One finds that CfO/sh kept up with inflation while dividend growth was short by about 130 bps. If this represented the future, real income would drop 12% over 20 years.
Had you invested $1M in the portfolio a year ago, you would have received somewhat more than $46k in dividends. Continuing to hold that same portfolio would produce $47.4k for 2025, ignoring future dividend increases.
With that, let’s look forward.
